

welcome back.
super pumped about this week’s memo.
the market’s moving differently now. conversations sharper. budgets expanding faster than expected.
as always, hit reply with thoughts. share this with someone wired like us.
lets dive in…..
the signals
ai + human GTM: the revenue frontier
source: Adam’s GTM Report | | date published: 01/31/2026
tag: infra / app / model
summary: solid analysis by Adam Schoenfeld. ai companies are STILL hiring human sdrs and enterprise sales talent despite years of automation predictions. 39% of ai companies with open gtm roles are hiring sdrs or sdr leaders, and there are 2x more enterprise ae roles open, which signals even more sdr hiring ahead. the enterprise push is real. one third of all gtm roles are enterprise focused, targeting 7+ year veterans with self sourcing skills and technical depth at $300–320k ote. clay, anthropic, coreweave, and langchain are building sdr functions from scratch in 2026, often hiring leadership before individual contributors. international expansion now spans 8-9 countries per company, with clear vertical specialization emerging, harvey in legal, elevenlabs in healthcare and government. companies are not replacing humans. they are learning a new playbook.
tactical breakdown:
founders: the implication is straightforward. budget for premium enterprise talent now. technical fluency is the moat. build your sdr leadership layer before scaling ic’s, coreweave is hiring directors to architect the function first. do not assume ai replaces humans in complex, multi threaded enterprise deals, the data shows the opposite. and consider vertical specialization.
gtm leaders: prioritize technical acumen, two thirds of roles now require it. watch the 2x ae to sdr ratio closely
investors: enterprise gtm buildout is a leading indicator of real revenue ambition. half of top ai companies now have enterprise roles open, paired with aggressive international expansion. expect higher gtm burn than traditional saas, so dig into each portfolio company’s human & ai gtm mix and efficiency metrics. companies building from scratch, clay, anthropic, langchain, will set new benchmarks for fde ratios and gtm efficiency. watch those experiments closely.
where’s the spend going?
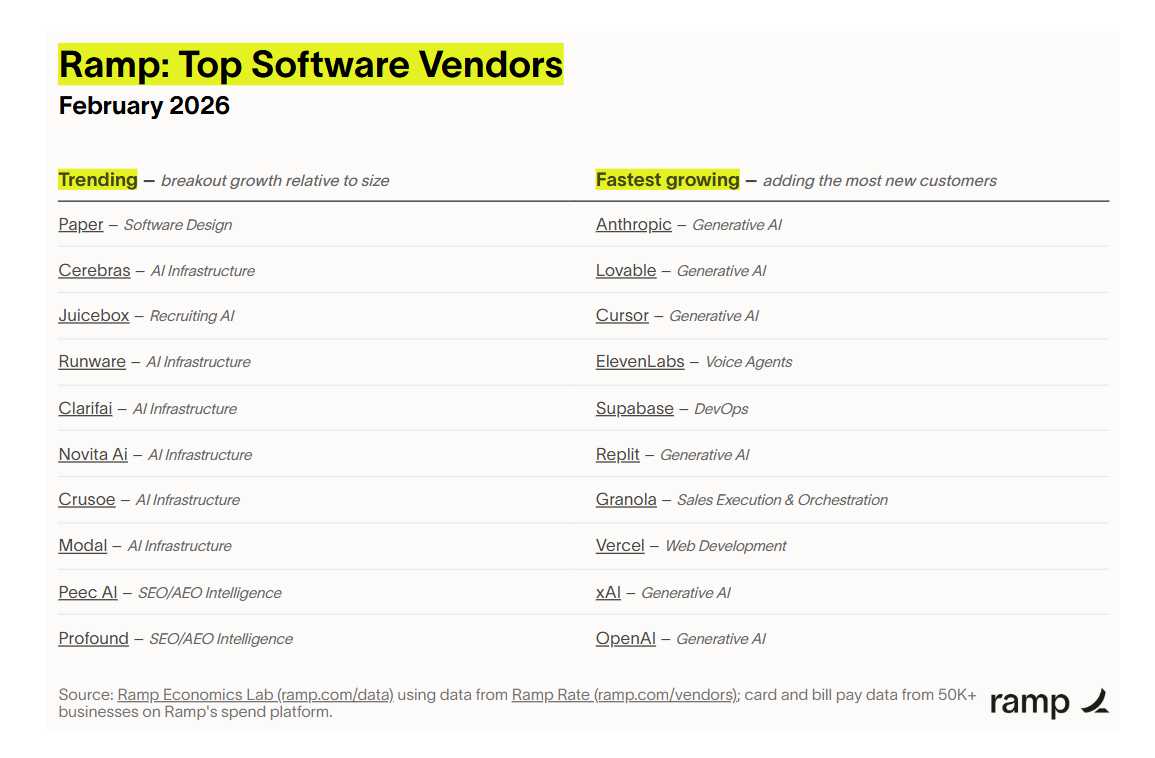
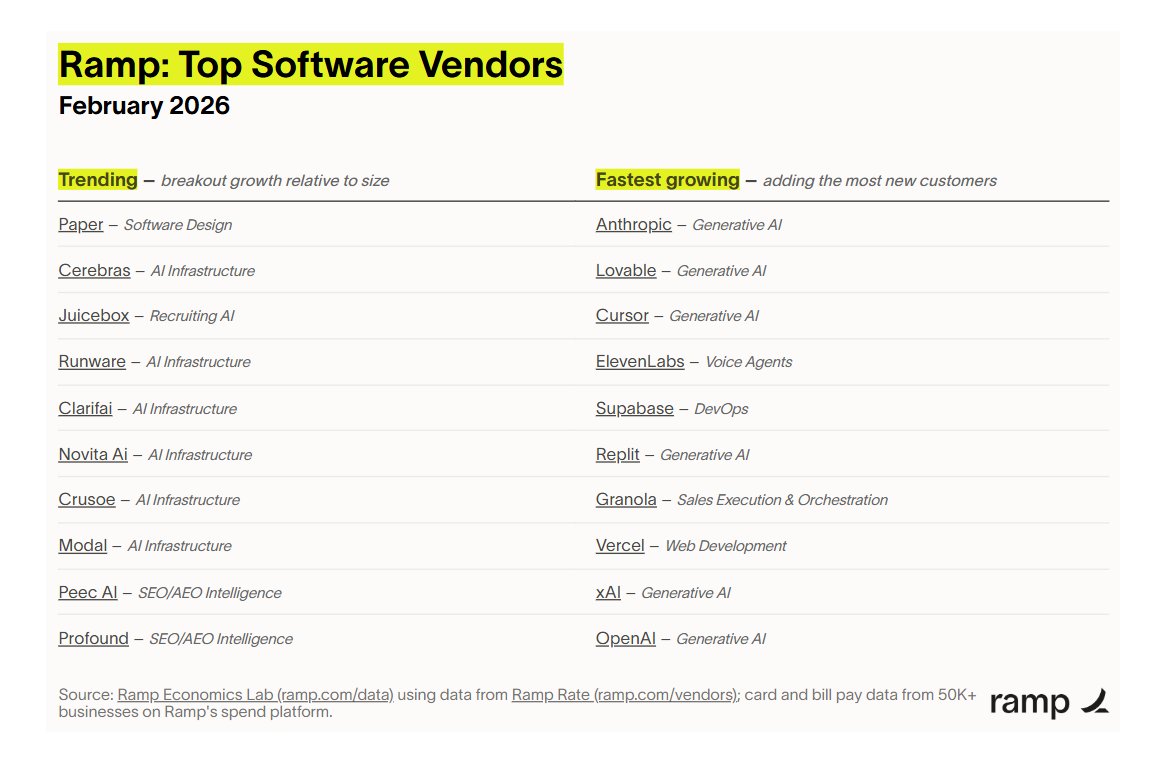
source: ramp economics lab | date published: 02/05/2026
tag: infra/ app / model
summary: Ara Kharazian from ramp publish a report ‘top SaaS vendors on ramp’, and the data speaks.. the fastest-growing vendors reveal three structural market shifts: first, foundation models are unbundling at the edges (cursor, lovable, replit thrive despite openai/anthropic competition). second, infrastructure sovereignty is turning into a board-level conversation as companies hit API cost ceilings (six trending vendors are infrastructure plays). third, AEO tools gain adoption faster than SEO historically did. anthropic leads absolute growth, but the ecosystem around it proves distribution, workflow integration, and cost optimization capture value. the meta-trend is vertical specialists are winning. the companies compounding right now solve one narrow, expensive problem exceptionally well.
tactical breakdown
founders: build for the unbundling. the big labs won’t capture the entire value chain. cursor and lovable are proof. pick one narrow, expensive problem. developer velocity. cost overruns. search visibility inside answer engines. own it end to end. vertical specialists with tight icp focus are pulling ahead. if you can materially reduce spend or introduce cost predictability, you are the budget. the is distribution.
gtm leaders: sell cost control. infrastructure vendors are winning conversations by showing API bill comparisons, cost reduction converts. marketing teams are budgeting for answer engine visibility, so stop positioning it as experimental. horizontal messaging is fading. specificity closes.
investors: recalibrate toward vertical depth. the foundation layer matters, but the fastest growers are specialized layers wrapping around it. workflow tools with strong ux are proving defensible even against platform competition. perhaps avoid generalists trying to do everything. back companies solving one painful, budget-backed problem for a narrow icp with 10x better workflow.
pricing ai without killing your margin
source: GTMnow | date published: 02/06/2026
tag: app / model
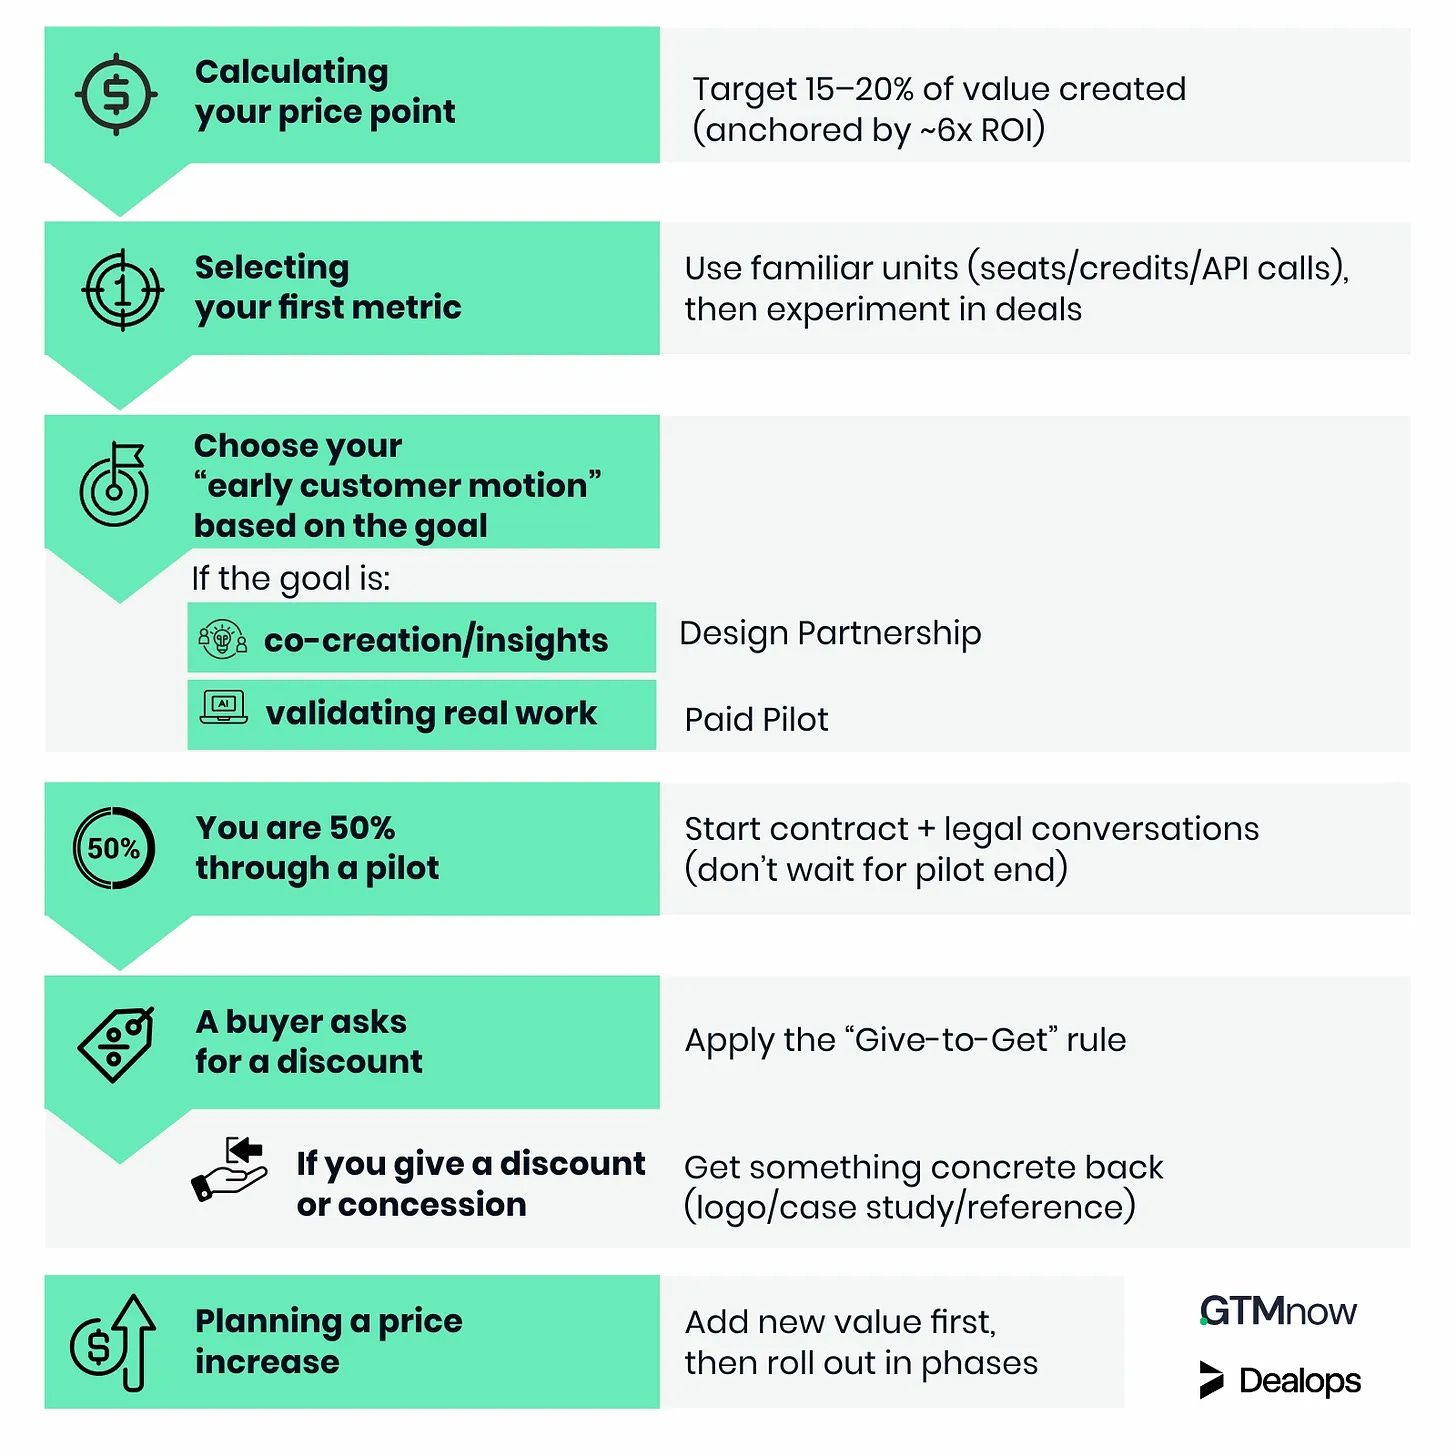
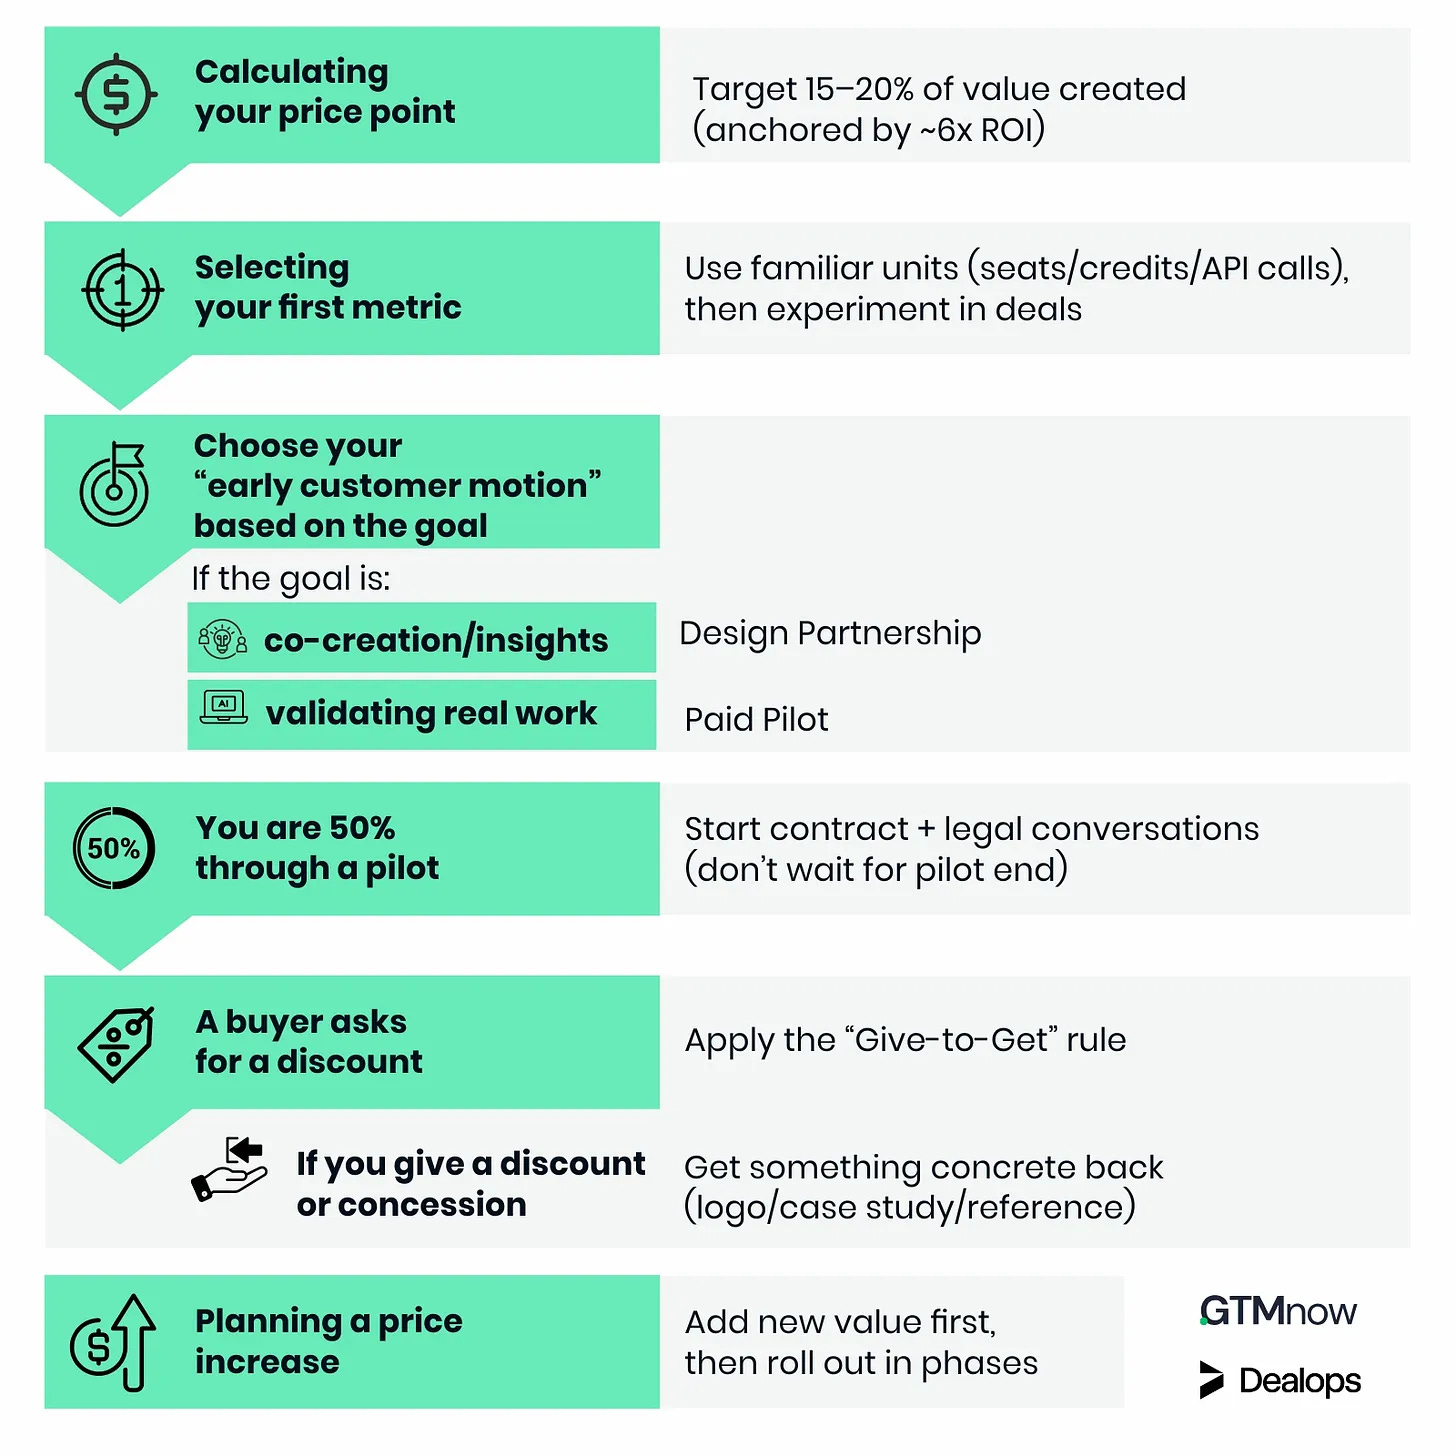
summary: top-notch report by Dealops and GTMnow. ai pricing starts with understanding where you create economic value and how much of that value you can capture. rule of thumb seems to be 15 to 20 percent of the value created, leaving the buyer with roughly a 6x return. resist the urge to jump straight into complex outcome-based pricing. begin with metrics customers already understand like seats, usage, credits, or api calls. separate learning from selling. design partnerships are free, tightly scoped, and explicitly about learning. pilots are paid, priced on your long-term metric, and set higher than feels comfortable because you will not raise prices from your pilot baseline. start contract conversations halfway through the pilot to avoid losing momentum between validation and procurement. your first ten deals are less about revenue and more about proof: logo rights, case studies, references. and never raise prices just because you can. raise them when you add new value.
tactical breakdown
founders: before you price, map the chain. what does your product change:
tickets resolved, hours saved, meetings booked, claims processed. then attach $$$ to that delta. if you can’t draw the line from usage to financial outcome, pricing will drift. start simple. familiar metrics to reduce friction and earn the right to evolve toward outcome-based models over time.
gtm leaders: early deals are serve a few purposes: logo rights, case studies, references, and structured feedback.. all carry value and should be negotiated intentionally. protect the spine of the deal: unit pricing, expansion pathways, and rejecting open-ended liability. when planning price increases, roll them out in phases, start with smaller segments, communicate early and directly, and tie every increase to visible new value.
investors: push portfolio companies to quantify the value chain early. what operational metric moves, and what is that worth? make pricing reviews part of board cadence, watch for metric lock-in. a weak pricing anchor, once embedded in contracts, becomes painful to unwind. help teams test metrics in early cohorts before they scale distribution around the wrong one. encourage paid pilots with explicit graduation paths and predefined commercial terms. that structure builds leverage and sets expectations.
enterprise ai leaderboard: no king yet
source a16z| date published: 01/30/2026
tag: infra / app / model
summary: a16z’s third annual cio survey of 100 global 2000 companies dropped.. hat tip to Sarah Wang, Shangda Xu, Justin Kahl. openai still leads with 78% production adoption, but anthropic has surged to 44% penetration, up 25% since may 2025, largely on the back of newer model releases. gemini is gaining across most use cases except coding. meanwhile, 81% of enterprises now use three or more model providers, up from 68% last year, signaling that multi-model is the default strategy. third-party ai apps are thriving despite app apocalypse narratives, while microsoft continues to leverage distribution through copilot and github. enterprise ai budgets have grown from $4.5m to $7m over two years and are projected to reach $11.6m in 2026. closed-source models are increasingly preferred, trust in frontier labs is rising, and reasoning models are accelerating adoption by enabling more agentic workflows with less prompt engineering. this is structural budget shift.
tactical breakdown:
founders: don’t optimize for a single model. enterprises are explicitly multi-provider, which creates opportunity in routing, orchestration, and governance layers. microsoft’s distribution edge is real, but platform shifts always create timing windows for ai-native players. r&d velocity is customer acquisition in an interesting way.
gtm leaders: lead with your most advanced models in token-heavy workflows like coding and data analysis. that’s where wallet share is moving fastest. horizontal use cases tilt toward incumbents, so if you’re up against microsoft, win on speed and depth. reasoning models are the wedge. 54% of cios say they accelerate adoption through higher accuracy and less prompt engineering. this is a land and expand market and expect budgets to grow in 2026.
investors: the top of the stack is hardening around openai, anthropic, and google, with switching costs rising as model r&d becomes distribution. but the application layer is far from dead. vertical workflows with intelligent model routing remain underbuilt. enterprise spend continues to outpace expectations. tam is expanding in real time.
the founder evolution paradox
source Chris Tottman| date published: 02/05/2026
tag: infra / app / model
summary: props to Chris Tottman this nails the founder evolution. as companies grow from startup to scale-up to maturity, founder’s job mutates. they must shift from brave warrior (close the deal. ship the feature. hire the first ten. decide fast) to wise monarch (build systems. delegate authority. let decisions happen without you) grow again, and the job changes once more. founders become the considered architect (design culture. shape incentives. think in decades) but early success can trap founders in behaviors that worked at 10 people become the bottleneck at 100. and lethal at 1,000. and most companies stall because the founder keeps leading like it’s year one. investors watch whether founders can evolve their identity alongside the company. great founders they integrate the modes. the question "what does the business need from me now?" and that evolution, more than product or capital, separates plateau from endurance.
tactical breakdown:
founders: perhaps run a monthly mode audit. list your last few decisions. how many required only you? that's your bottleneck score and build that system that runs without you. repeat monthly until you're bored.
gtm leaders: when proposing new gtm processes, show how they create predictability the business needs while honoring the founder's instincts. your ability to demonstrate systematic revenue generation helps founders trust delegation and transition to wise monarch leadership.
investors: guide founders through identity transitions as a core value add. normalize the identity death and provide a roadmap accelerates founder growth and de-risks the investment.
data drop
50,000+ businesses tracked, 6 of 10 trending companies are ai infrastructure.
when pricing an ai product, buyers typically purchase at around 6x the roi your product delivers. vendors usually capture only 15-20% of the value their product creates.
early-stage pilots are often 60 days long, and founders should start contract discussions around day 30 to maintain momentum.
the first 10 deals are crucial for building proof, references, and credibility with customers and investors.
while pricing changes historically occurred every 5-10 years, in AI startups they can happen as early as seed and series a rounds.
a16z survey (enterprise ai adoption) 78% of surveyed enterprises use openAI models in production. anthropic: 44% in production, 63% including testing; largest share increase since May 2025 (+25%). multiple models: 81% of enterprises use three or more model families, up from 68% last year.
microsoft dominates enterprise ai applications: microsoft 365 copilot leads enterprise chat. and github copilot leads coding.
65% of enterprises prefer incumbent solutions for trust, integration, and procurement simplicity.
llm spend: ~$4.5M → ~$7M over two years, expected to rise another ~65% to ~$11.6M.
application spend: expected ~$3.9M, actual ~$6M.
despite predictions that AI would replace SDRs, top AI-native companies are building SDR functions. 39% of AI companies with open GTM roles are hiring SDRs or SDR leaders and18% are hiring leadership-level SDR roles.
~1/3 of all open GTM roles at top AI companies are enterprise-focused.
50% of companies with open GTM roles have at least one enterprise role open.
where to be
mixture of experts by Sarah Guo ⚡️ Greylock · sf · feb 19 · focus: ai builders, founder stories, networking, and career opportunities. hear from founders at sunday robotics, harmonic, trajectory, treehouse labs, worktrace. why go: first off.. Sarah is a beast and she is networked with/investing in some of the hottest companies in AI today. meet fellow builders, discover early-stage startups, and explore career-making opportunities in ai. high signal for founders, talent, and networkers who want to connect with the next wave of ai startups. event link
claude code for everyone · sf · feb 17 ·focus: ai development made accessible, agentic workflows, gtms, and distribution strategy. hear how claude code powers execution without terminal commands, enabling faster iteration, shipping, and adoption. why go: understand the orchestration era of ai, where gtms define the moat. founders, operators, and sales leaders will get hands-on insights into speeding product adoption and early-stage distribution. event link
future of ai · sf · feb 16 focus: startup innovation, ai, infra, early-stage product velocity, and scaling teams. fireside with rob ferguson (cto, microsoft for startups) guided by mayra ceja, covering enterprise, corporate venture, and emerging tech insights. why go: get candid frameworks founders can use immediately, understand how large partners evaluate early-stage teams, and hear rare insights from a plugged-in technical leader shaping ai’s future. event link
closing shot
the foundation layer is hardening fast, but the application layer is still wide open, and there’s some serious land grab available. Those who can capture operational delta can carve out a real business despite the big model providers.
and gosh, I feel like a broken record at this point. But technical acumen is absolutely critical when building out your GTM program. yes, you need to leverage the tools, but the humans you hire all also need to talk the talk when it comes to your technology.
peace and love!
Great roundup! Appreciate the GTMnow edition highlight